Smarter repayments, greater savings
Pay less interest.
Own your home sooner.
I help Malaysian homeowners cut interest and years off their home loan with FIS Advisory’s repayment strategy. Same bank, same loan, no refinancing. Across FIS cases, homeowners typically pay 30% to 75% less interest.
No bank change
Keep your existing loan and bank.
Pay your bank directly
FIS never handles your money.
No refinancing
No new legal or valuation fees.
Standard bank plan vs FIS 50
Projection from my FIS Estimated Payment Report. Your result depends on your own loan.
Since 2014
FIS Advisory: Malaysia's mortgage interest optimisation specialists
Major Malaysian banks
Works with the loan you already have
No refinancing
No bank switching, no new loan agreement
Authorised FIS agent
Dylan Goh, agent code C-210-350
Is your mortgage working as hard as you are?
Is your mortgage really on track?
Most homeowners pay faithfully every month and assume the loan is shrinking on schedule. Often it is not.
Your balance barely moves
Years of instalments, yet the outstanding amount drops far slower than you expected. In the early years, most of each payment goes to interest.
Rate hikes quietly add years
When OPR and your bank's base rate go up but your instalment stays the same, your tenure can stretch without anyone telling you.
Extra cash, no clear plan
Random lump sums help a little, but without a structure built around how your bank calculates interest, you rarely get the full benefit.
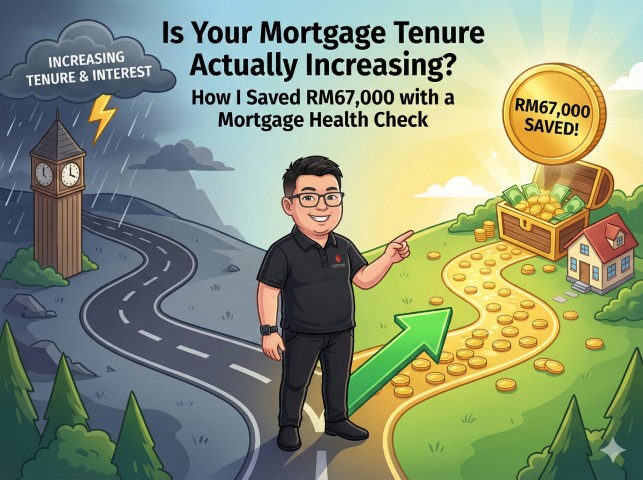
That happened to me. My own loan had stretched by 72 months before anyone ran the numbers.
Why I do this
I was an FIS client before I became an agent
For 66 months I paid RM768 every month on my Hong Leong home loan, RM50,688 in total. When FIS ran an Estimated Payment Report on my loan, I found that OPR and BLR increases had quietly extended my tenure by 72 months.
With the FIS 50 plan, my remaining tenure dropped from 366 to 183 months and my projected interest fell from RM134,084 to RM67,042. That is why I joined FIS Advisory: so other homeowners find out sooner than I did.
Our 5-step process
How FIS works
From your first conversation to verified savings. Typically 30% to 75% less interest paid.
Review
Send your latest loan statement and offer letter. We check how much interest you are on track to pay.
Plan
FIS designs a repayment plan (FIS 30, 50 or 75) around your goals and monthly cash flow.
Implement
I walk you through the simple setup. Your loan, your bank and your account stay the same.
Execute
You pay your bank directly each month, following your plan. The savings build up over time.
Verify
We compare your bank statements against the plan regularly to confirm the savings are real.
Your personalised roadmap
Three ways to pay less interest
After reviewing your loan, FIS recommends the plan that fits your goals and cash flow. You never have to guess.
FIS 30
Smart Start
Start saving, even on a tighter budget.
- Around 30% less interest over time
- Shorter tenure with a small monthly adjustment
- Simple and easy to keep up
Best forHomeowners who want to start without financial pressure.
Most popular
FIS 50
Accelerator
Balance today’s comfort with a faster payoff.
- Around 50% less interest over time
- A meaningfully shorter tenure
- Steady progress without stretching cash flow
Best forHomeowners who want the best balance of savings and affordability.
FIS 75
Fast Track Freedom
Maximise savings and finish much sooner.
- Up to 75% less interest over time
- A significantly shorter tenure
- Flexible access to funds when needed
Best forHomeowners who want the fastest path to being mortgage-free.
Percentages are typical outcomes across FIS cases, not a guarantee. Your plan and projected savings are confirmed only after your loan is reviewed.
FIS customer success stories
Real homeowners. Real results.
Results published by FIS Advisory from its customers. Every loan is different, so your own plan and projected savings are confirmed only after a review.
Loan completed
Chris Chia
Financial clarity
A businesswoman who did not want to tie up a lump sum, Chris started out sceptical and compared her FIS ledger with her bank statement every six months. The figures matched, and she finished a 28-year loan in 7. She is now optimising two more loans.
Loan completed
Clara Hoh
Freedom as risk management
Clara did not want to depend on her income for 21 years while carrying the risk of illness or retrenchment. Following the FIS ledger, she cleared her home loan in 10 years and saved about half the interest.
Loan completed
Nurul
Financial freedom
Nurul used to focus only on paying each month. Once she understood how her loan worked and followed the FIS ledger consistently, she completed a 30-year mortgage in 7½ years.
On track
Mohamed Aziz
I wish I knew earlier
After 12 years of faithful payments his balance had barely moved. The past could not be changed, but FIS built a plan around his cash flow to cut the remaining tenure in half.
On track
Jason
Starting smart
A first-time buyer on a tight early-career budget, Jason started right after vacant possession instead of waiting. His plan takes 10½ years off a loan that would have run into his mid-60s.
On track
Kelvin
Loan clarity
Kelvin paid as instructed but could not see where his money went. His FIS ledger now shows what to pay each month and how each step cuts interest, on track to finish 14 years sooner.
Stories, results and photos: FIS Advisory Sdn Bhd, fisadvisory.com
Free Mortgage Health Check
When will your home loan really end?
Enter the numbers from your loan statement and see where you really stand. It takes about 2 minutes and works in English, Bahasa Malaysia and 中文.
- How much of what you have paid went to interest vs principal
- Whether your loan is on track to finish on time
- The instalment needed to finish on schedule
- A PDF report you can keep, plus an optional free consultation
Questions
Quick answers
Do I need to refinance or change banks?
No. FIS works on how you repay the loan you already have. Your bank, your loan account and your loan agreement stay the same, so there are no new legal or valuation fees.
How much could I save?
It depends on your loan amount, rate, remaining tenure and how your instalments are applied. Across FIS-tracked cases, the average customer saved 48.8% of their mortgage interest and cut their tenure by about 52%. For suitable cases the typical range is 30% to 75%, but every loan is reviewed individually before any figure is promised.
Is the review really free? Do I have to sign up first?
Yes, the review is free and there is no obligation. You see what the analysis says about your loan first, and only then decide whether to go ahead.
Does FIS handle my money?
No. You keep paying your bank directly, from your own account. FIS designs and tracks the repayment plan; it never collects your instalments.
What do I need to get started?
Your latest loan statement and your letter of offer. For an existing loan, the dates and amounts of your last three instalments help too. You can also start with the online Mortgage Health Check using just the numbers from your statement.
Find out where your home loan really stands
Start with the free online Health Check, or send me a WhatsApp and I will look at your loan with you. No obligation, no pressure.