How it works
A smarter way to repay the loan you already have
FIS Advisory doesn’t sell you a new loan. We look at how your existing home loan really behaves, then build a repayment plan around the way your bank calculates interest, so more of every ringgit goes to your principal.
Why homeowners overpay
Your instalment is built for the bank, not for your savings
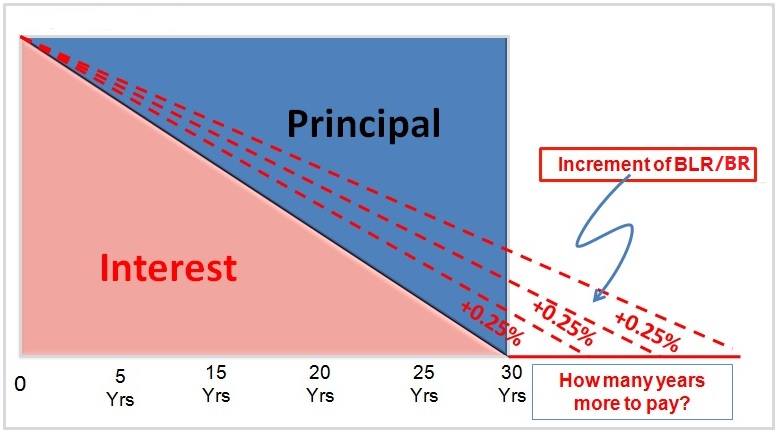
Malaysian home loans charge interest on your outstanding balance every day. In the early years, most of each instalment goes to interest and only a small part reduces what you owe. That is why the balance seems stuck even when you never miss a payment.
When OPR and your bank’s base rate rise, the interest share grows. If your instalment stays the same, the loan simply takes longer to finish. Each +0.25% can quietly add months, or years, to your tenure.
- Relying on bank calculators that show theory, not your real payments
- Making random extra payments without knowing how the bank applies them
- Assuming refinancing is the only way to pay less interest
Not refinancing. Not restructuring.
How FIS is different
Most people think there are only two ways to pay less interest. There is a third, and it does not need a new loan or your bank’s approval.
| Refinancing | Restructuring | FIS repayment strategy | |
|---|---|---|---|
| What it is | A new loan, usually with a new bank | New terms on your loan, usually for borrowers in difficulty | A structured repayment plan on the loan you already have |
| Bank approval | Needed | Needed | Not needed |
| Legal, valuation, stamp duty | Usually | Sometimes | None, there is no new loan |
| Your bank and loan account | Change | Same bank, new terms | Stay exactly the same |
| Interest and tenure | Depends on the new rate; tenure often resets | Often a longer tenure to lower the instalment | Less total interest and a shorter tenure |
Our 5-step process
From review to verified savings
Plans are built on a ledger that mirrors your bank’s own calculation, and adjusted when OPR or your bank’s rates change.
Review
Send your latest loan statement and offer letter. We check how much interest you are on track to pay.
Plan
FIS designs a repayment plan (FIS 30, 50 or 75) around your goals and monthly cash flow.
Implement
I walk you through the simple setup. Your loan, your bank and your account stay the same.
Execute
You pay your bank directly each month, following your plan. The savings build up over time.
Verify
We compare your bank statements against the plan regularly to confirm the savings are real.
Your personalised roadmap
FIS 30, FIS 50 or FIS 75
You do not have to choose. After reviewing your loan, cash flow and goals, FIS recommends the plan that creates the most value for you.
FIS 30
Smart Start
Start saving, even on a tighter budget.
- Around 30% less interest over time
- Shorter tenure with a small monthly adjustment
- Simple and easy to keep up
Best forHomeowners who want to start without financial pressure.
Most popular
FIS 50
Accelerator
Balance today’s comfort with a faster payoff.
- Around 50% less interest over time
- A meaningfully shorter tenure
- Steady progress without stretching cash flow
Best forHomeowners who want the best balance of savings and affordability.
FIS 75
Fast Track Freedom
Maximise savings and finish much sooner.
- Up to 75% less interest over time
- A significantly shorter tenure
- Flexible access to funds when needed
Best forHomeowners who want the fastest path to being mortgage-free.
Percentages are typical outcomes across FIS cases, not a guarantee. Your plan and projected savings are confirmed only after your loan is reviewed.
FIS customer success stories
Loans already paid off
Results published by FIS Advisory from its customers. Every loan is different, so your own plan and projected savings are confirmed only after a review.
Loan completed
Chris Chia
Financial clarity
A businesswoman who did not want to tie up a lump sum, Chris started out sceptical and compared her FIS ledger with her bank statement every six months. The figures matched, and she finished a 28-year loan in 7. She is now optimising two more loans.
Loan completed
Clara Hoh
Freedom as risk management
Clara did not want to depend on her income for 21 years while carrying the risk of illness or retrenchment. Following the FIS ledger, she cleared her home loan in 10 years and saved about half the interest.
Loan completed
Nurul
Financial freedom
Nurul used to focus only on paying each month. Once she understood how her loan worked and followed the FIS ledger consistently, she completed a 30-year mortgage in 7½ years.
Stories, results and photos: FIS Advisory Sdn Bhd, fisadvisory.com
Getting started
What you will need
- Your latest home loan statement
- Your letter of offer (all pages)
- Existing loan: dates and amounts of your last 3 instalments
- New loan: your first instalment date
Not ready to share documents? Start with the free Mortgage Health Check using the numbers on your statement.
Who it is for
Is this right for you?
- Homeowners with an existing housing loan from a Malaysian bank
- Property investors who want a shorter tenure and less interest
- Malaysians and Singaporeans with a Malaysian property loan
- Anyone whose balance isn't falling as fast as expected
- Anyone who wants extra payments to work harder
Your data is safe
Documents are used only to calculate and prepare your proposal, in line with the PDPA. If you do not go ahead, they are discarded and never used for marketing.
See what FIS could do for your loan
Run the free Health Check in about 2 minutes, or WhatsApp me your questions. No obligation.